
HOME |
AUTO |
CONDO |
MOTORCYCLE & RV |
UMBRELLA |
BOAT |
RENTERS |
COMMERCIAL |
HOME | AUTO | CONDO | MOTORCYCLE & RV | UMBRELLA | BOAT | RENTERS | COMMERCIAL |
FLOOD INSURANCE IN FLORIDA
Because your homeowners policy stops at the waterline.
Standard homeowners and renters policies don’t cover flood damage. We compare NFIP and private flood options for Gulf Coast homes, condos, and rentals — and explain your flood zone in plain English.
Fast, Local Claims Support
20+ Carriers Compared
Locally Owned
& Operated
COVERAGE
Flood insurance, built for Florida’s Gulf Coast
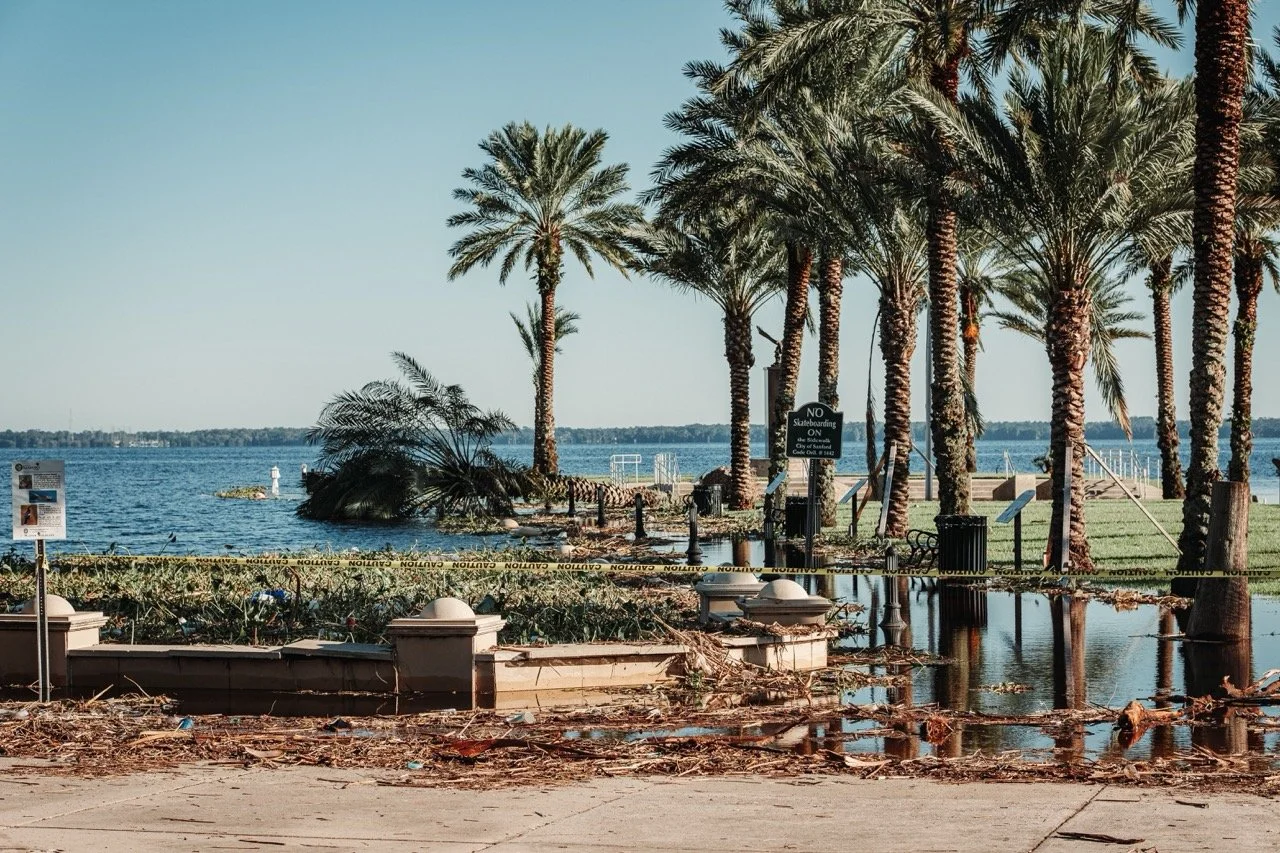
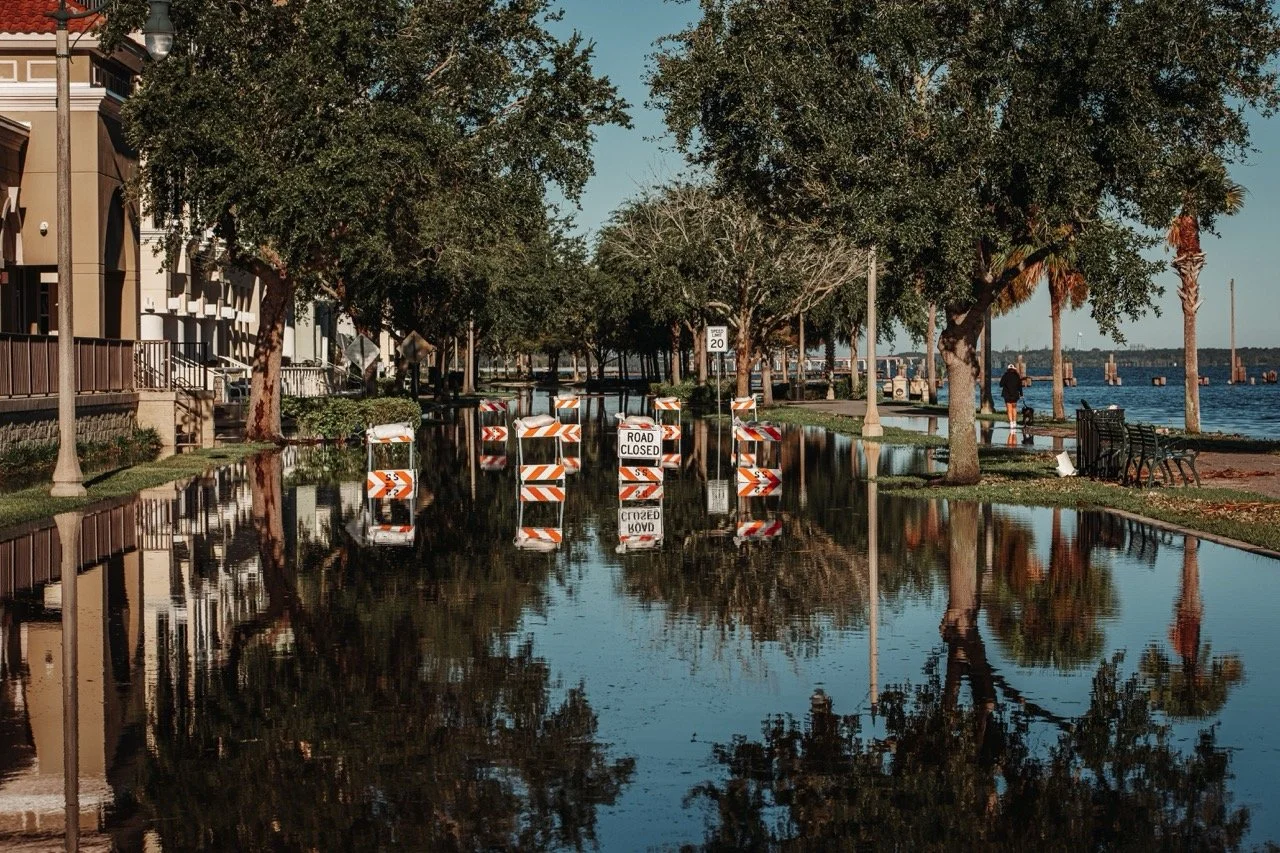
Storm surge, tropical downpours, and overflowing canals can reach homes in any flood zone. A flood insurance policy covers the water damage your homeowners or renters insurance won’t.


BUILDING COVERAGE
Repairs your home’s structure, walls, and systems after a flood.

CONTENTS COVERAGE
Protects your belongings from floodwater — for owners and renters.
STORM SURGE &
RISING WATER
Covers the storm surge and rising water homeowners policies exclude.

NFIP OR
PRIVATE FLOOD
We compare federal NFIP and private flood policies for you.
WHY WARNER
Local roots. Real People. Coverage you can count on.
Captive agents can only sell you one company's product. We compare over 20 carriers and find the one that actually fits your life. When you have a claim, we're the one in your corner, not just a name on a policy.


7+
Years in Florida Insurance
20+
Carrier Partners Compared for You


Ready to see what better coverage looks like?
MORE WAYS WE CAN COVER YOU
Flood coverage works best alongside the rest of your policies.
Flood insurance fills one gap. Here’s where else Warner Insurance can help protect your Florida home and life.
HOMEOWNERS INSURANCE
Wind, hurricane, and liability coverage for Gulf Coast homes — the policy your flood insurance is built to sit beside.
AUTO INSURANCE
Flood damage to your car falls under comprehensive auto coverage, not flood insurance. We’ll make sure you have it.
RENTERS INSURANCE
Protect your belongings and liability in an apartment or rental home, then add contents-only flood coverage.
SERVICE AREA

We've got Florida's Gulf Coast covered.
We write policies across the entire state, but our roots are on the west coast — Manatee, Sarasota, Hillsborough, Pinellas, Charlotte, Pasco, Lee, and Collier counties.
Here are a few of the communities we work in most:

Venice
Siesta Key
Sarasota
Bradenton
Lakewood Ranch
Anna Maria Island
Clearwater
St. Petersburg
Tampa
SAVE ON FLOOD COVERAGE
Ways to Lower your Flood Insurance Premium
Worried about what flood coverage could run you? We’ll help you check your home’s features to see where you might be able to save.
ELEVATION CERTIFICATE
Documenting your home’s elevation can help qualify you for a better flood rate.
FLOOD MITIGATION
Flood vents, elevated utilities, and other upgrades can reduce your risk and your premium.
COMMUNITY RATING SYSTEM
Many Florida communities earn NFIP discounts for residents through FEMA’s CRS program.
HIGHER DEDUCTIBLE
Choosing a higher deductible is one of the simplest ways to lower your annual cost.
Frequently Asked Questions about Flood Insurance in Florida
FAQ
-
If you have a federally backed mortgage on a home in a high-risk flood zone, your lender will require it. Citizens Property Insurance is also phasing in a requirement: in 2026 it applies to Citizens homeowners policies with wind coverage on homes valued at $400,000 or more, and starting January 1, 2027 it applies to those policies regardless of home value.
-
Not necessarily. While some homeowners policies cover water damage from burst pipes and other internal causes, the vast majority exclude flood damage from hurricane storm surge. Wind damage is usually covered, but rising water requires a separate flood insurance policy.
-
Yes. NFIP flood policies typically take effect 30 days after purchase, with limited exceptions such as coverage bought when closing on a home. Private flood waiting periods vary by carrier, so don’t wait until a storm is in the forecast!
-
It’s worth considering. A significant share of flood claims come from properties outside high-risk zones, and coverage in moderate- and low-risk areas often costs less than people expect!
-
National Flood Insurance Policies (NFIPs) are backed by the federal government and cap residential coverage at $250,000 for the building and $100,000 for contents. Private flood carriers may offer higher limits, additional living expenses, and different waiting periods. We’ll compare both for your property.
-
Yes. Renters can buy contents-only flood coverage for their belongings, and condo owners can insure their unit and contents on top of the association’s master policy.


Get a Florida flood insurance quote in minutes.
Talk to a local agent today — no pressure, just honest coverage advice.